Mortgages
Interest rate predictions NZ 2026 & 2027: What economists forecast
Discover where interest rates are headed in 2026 and beyond so you can make informed decisions for your property portfolio.
Mortgages
6 min read
Investors are always asking me: “How long should I fix my mortgage interest rate for?”
But no one knows where rates will go month-to-month, let alone year-to-year.
Sure, experts provide forecasts ... but we can't predict the future.
Things happen, and interest rates change.
In 2020, Covid turned the world upside down. Then inflation sent interest rates soaring. Now, in 2026, global conflicts are causing more uncertainty.
And who knows what will happen next?
So, with all this uncertainty, what's better – the 1, 2, 3 or even the 5-year fixed interest rate?
In this article, you'll learn 3 strategies to help you decide how long to fix your mortgage for.
First, what are you actually trying to achieve when choosing a mortgage interest rate?
Usually, it's not about getting the lowest rate today.
It's about getting the lowest average interest rate over the next 5 years. That's the longest you can usually fix your mortgage for.
Right now, the 1-year rate is cheaper than the 5-year rate.
But if interest rates rise over the next few years, fixing for 5 years today could turn out to be the better deal.
On the other hand, if rates fall, you could end up paying more than someone who fixed for a shorter time.
The trouble is, nobody knows exactly what interest rates will do.
So, here are 3 strategies you can use to decide how long to fix your mortgage for.
One option is to choose the 1-year interest rate every year. No matter what.
Over the last 20 years that would have given you the lowest rate on average.
Let’s say you fixed for 1 year every year for the last 20 years.
Sure, sometimes you’ll pay a higher interest rate.
Locking in for 5 years back in 2004 would have given you a lower rate between 2006 and 2008.
That’s because the 1-year rate jumped from 6.9 to 9.7% in just 4 years.
But then the 1-year rate went down quickly. So, over time the 1-year rate has been cheaper than the 5-year rate. So, this strategy works for investors who say, “I don’t know where interest rates will go. Locking in for 1-year has been a good strategy in the past. I’m going to do that today.”
You won’t always come out ahead, but over time you likely will.
Let’s say you had a $500k mortgage (on P+I) back in 2004. If you locked in the 1-year rate every single time, you would have saved:
Big savings.
If you don’t want to put all your eggs (or mortgage) in the same fixed-rate basket – you can split it up.
Let’s say you’ve got a $500k mortgage.
Some investors will put $250k on 1-year fixed. They’ll fix another $250k on a different term (e.g. 2-year or 5-year).
If you do this, you’ll get an average of the market over time.
That does mean you’ll never get the absolute lowest interest rate, but if you choose the “wrong” interest rate, then you’re only half wrong.
So this strategy works for investors who say, “I don’t know where interest rates will go. Let me hedge my bets.”
In 2023, an investor fixed half their mortgage for the 5-year fixed when it was 2.99%. They fixed the rest for 1-year. They’re now paying over 7% on one part of their mortgage, but are still paying under 3% for the other part.
They’re happy. Their interest rate is about 5% (on average). They’re stoked. It’s a win for them.
Right now, the 1-year rate is cheaper than the 5-year rate.
As at October 2026, the lowest advertised 1-year rate is 4.95%, compared with 5.49% for 5 years.
So, why would you choose the more expensive 5-year rate?
And how far would interest rates need to rise before fixing for 5 years turns out to be the better deal?
Here are the numbers:
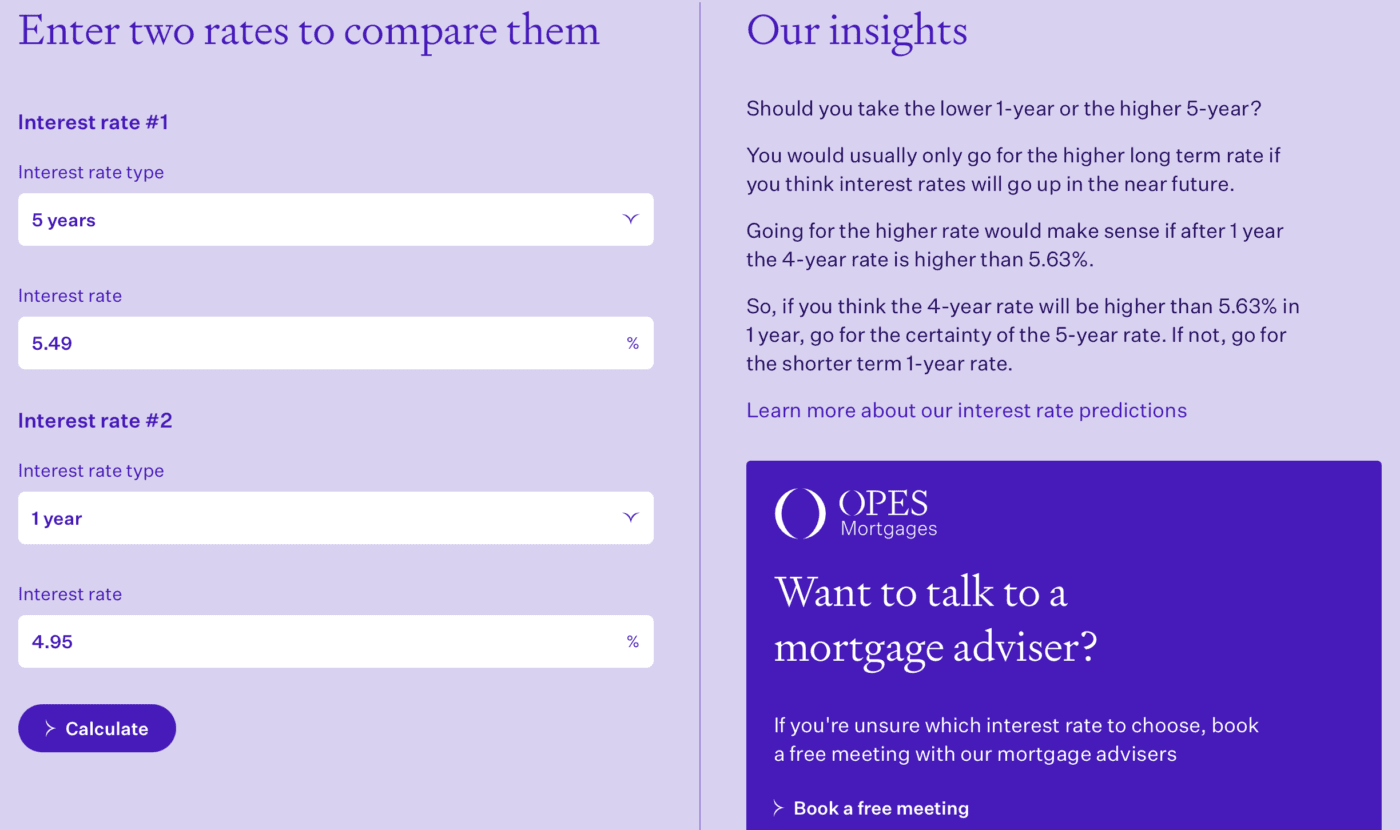
You’d need to get an average rate under 6.20% over the following 4 years for the 1-year rate to be worth it.
So ask yourself: “Once my first year is up, could I get an average interest rate of less than 6.20% (on average) for the next 4 years?”
If you think the answer is “yes”, go for the 1-year.
If you think the answer is “no”, take the 5-year.
The purpose isn’t to guess the interest rate precisely. It’s about giving you a frame of reference so you can decide which rate to choose.
The right strategy for you will depend on 3 things:
As a rule of thumb:
Remember, it's not necessarily about getting the lowest rate today. It's about getting the lowest average rate over the next few years.
Right now, the 1-year rate is cheaper than the 5-year rate.
But what if interest rates rise? You might wish you'd locked in for longer.
Take 2021, for example.
Back then, you could fix your mortgage for 5 years at 2.99%.
It wasn't the cheapest rate available at the time. But looking back, it was a fantastic deal.
That's why trying to predict interest rates is so tricky.
You've also got to ask yourself how comfortable you are with uncertainty.
We call this the "sleep test".
Some people think: "I'm not worried about getting the lowest rate. I just want certainty. So, I'm going to fix for longer."
And that's a perfectly reasonable decision.
If worrying about interest rates changing keeps you up at night, you might prefer to fix for longer.
That way, you know exactly what your mortgage repayments will be for the next few years.
Sure, you might pay a little more. But for some investors, that peace of mind is worth it.
You can't always afford the interest rate you want.
Personally, I prefer fixing for 1 year. That works for me.
And right now, the 1-year rate is cheaper than the 5-year rate.
But that doesn't mean everyone should fix for 1 year.
What happens if interest rates rise when it's time to refix?
Let's say you have a $500,000 mortgage.
If interest rates go up by 1%, that's an extra $5,000 a year in interest. Or around $96 a week.
Could you afford that?
If your budget is already tight, fixing for longer might give you more certainty.
But if you've got room in your budget to handle higher repayments, you might be more comfortable fixing for a shorter term.
The bottom line? The best interest rate strategy isn't always the one that saves you the most money. It's the one that works for your budget and lets you sleep at night.
Gain valuable insights on your interest rate by using our interest rate calculator.
Compare two interest rates now
Mortgage broker for over 10 years, property investor and Managing Director at Opes Mortgages
Peter Norris, a certified mortgage adviser with 10+ years of experience, serves as the Managing Director at Opes Mortgages. Having facilitated over $1.2 billion in lending for 2000+ clients, Peter is a respected authority in property financing. He's a frequent writer for Informed Investor Magazine and Property Investor Magazine, while also being recognized as BNZ Mortgage Adviser of the Year in 2018 and listed among NZ Adviser's top advisers in 2022, showcasing his expertise.
This article is for your general information. It’s not financial advice. See here for details about our Financial Advice Provider Disclosure. So Opes isn’t telling you what to do with your own money.
We’ve made every effort to make sure the information is accurate. But we occasionally get the odd fact wrong. Make sure you do your own research or talk to a financial adviser before making any investment decisions.
You might like to use us or another financial adviser