Property Investment
Quiz: Should I invest in growth or yield properties?
Find out if you should invest in growth or yield properties
Property Types
6 min read
Author: Nefe Marson
Financial adviser at Opes. Formerly a senior adviser at one of NZ largest investment firms. Owned 3 properties by 30.
Reviewed by: Ed McKnight
Resident Economist, with a GradDipEcon and over five years at Opes Partners, is a trusted contributor to NZ Property Investor, Informed Investor, Stuff, Business Desk, and OneRoof.
Property investment comes with a trade-off:
Put simply: more growth usually means less yield. More yield usually means less growth.
So, which one should you invest in?
Both can play a role in your property portfolio. But the right choice depends on your goals and where you are in your investment journey.
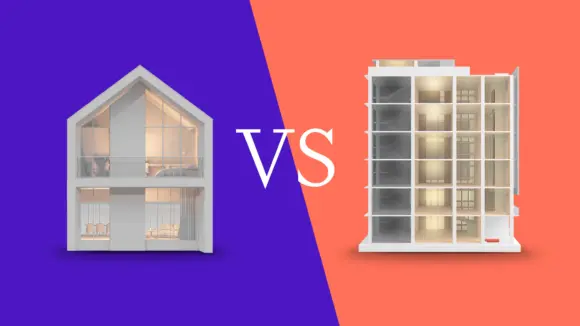
Here are the main differences:
| Growth property | Yield property | |
| Main goal | Build wealth through the house going up in value | Generate more income through rent |
| Capital growth | Higher | Lower |
| Rental yield | Lower | Higher |
| Cashflow | Often requires a larger top-up | Usually requires a smaller top-up |
| Typical property | House or townhouse | Dual-key or other high-yield property |
| Often suits | Investors building wealth | Investors who need more cashflow |
In this article, you'll learn how these differences play out in the numbers, and how to decide which type suits you.
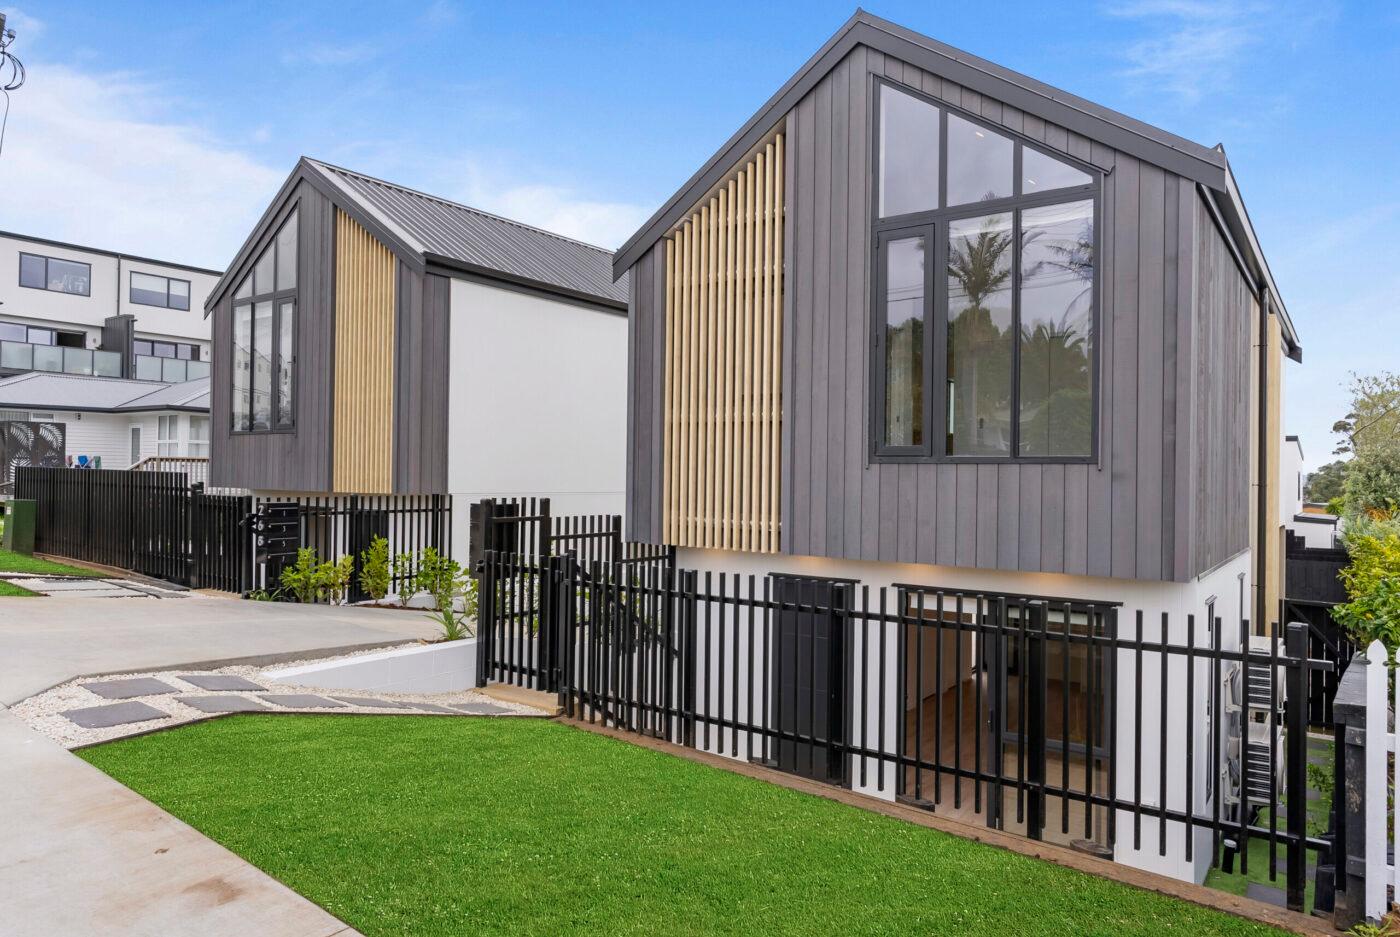
Growth properties tend to be houses and townhouses in a good area or neighbourhood.
Often, they're the sort of homes that owner-occupiers want to live in.
That part is important. Because, when you eventually sell, you're not just relying on investors to buy your property. You're also appealing to people looking for somewhere to live.
This can mean more potential buyers and stronger demand for your property.
And over time, that demand can help push property values higher.
Here's an example of what would be considered a growth property:
A yield property tends to earn more rent for its purchase price. But, they don’t go up in value as fast.
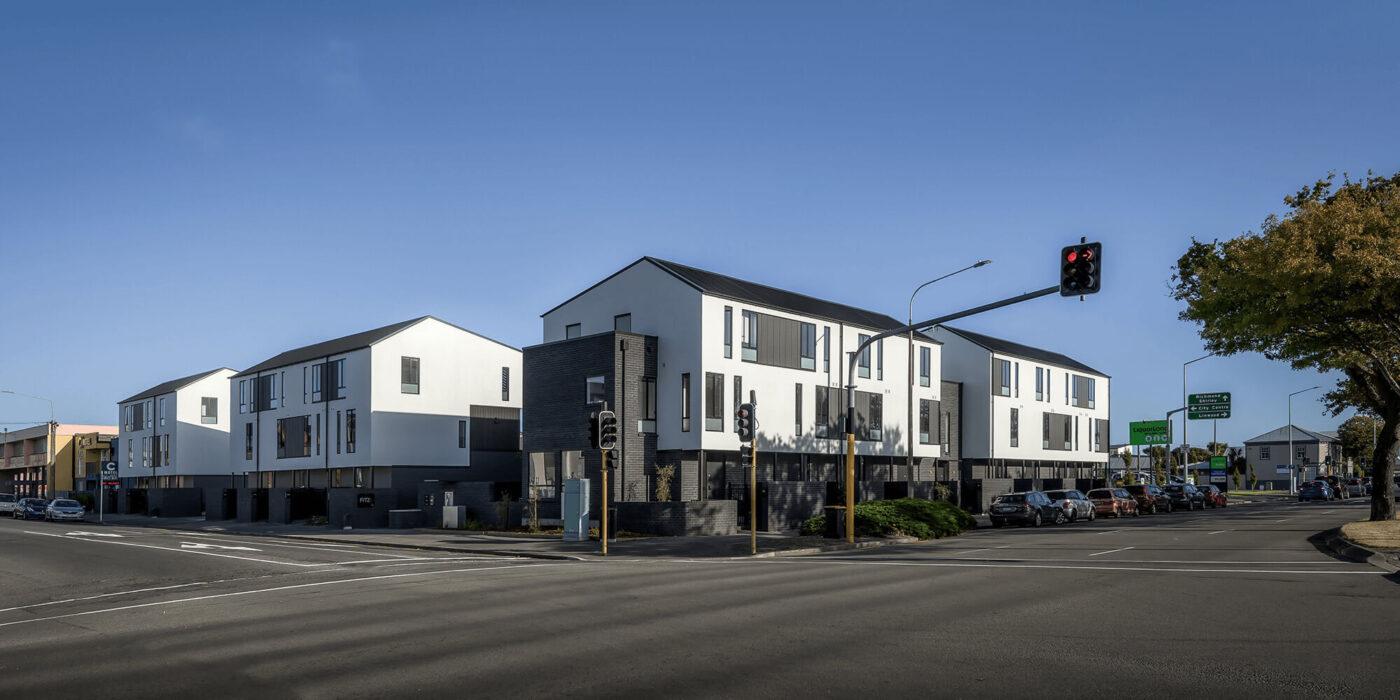
A dual-key property is a good example of a yield property.
That's where you have two separate living spaces within one property. Each can be rented to a different tenant.
That means you can earn rent from two tenants rather than one.
This can make the property attractive to investors who want more rental income.
But it may be less attractive to families looking for a home to live in.
That's one reason why yield properties don’t tend to go up in value as fast.
Here's an example of what would be considered a yield property:
More from Opes:
Growth properties have the potential to build more wealth over time. But there’s a catch.
They usually require more money from you along the way.
That's because growth properties often start out negatively geared. The rent doesn't cover all the costs, so you need to top up the difference.
Here’s an example of how growth vs yield stack up over 15 years:
| Yield property | Growth property | |
| Original value | $719,000 | $729,000 |
| Gross yield | 6.7% | 4.4% |
| Capital growth rate | 3% | 5% |
| Starting cashflow | -$211/week | -$383/week |
| How long negative cashflow lasts | 8 years | 15+ years |
| Cashflow invested over 15 years | $36,172 | $141,817 |
| Wealth built after 15 years (capital growth – cashflow) | $365,007 | $644,722 |
In this example, the growth property builds $279,715 more wealth over 15 years. That’s after accounting for the bigger top-ups.
But there's a catch.
You also need to put in an extra $105,645 to cover the property's costs along the way.
That's the trade-off.
The yield property costs less to hold and becomes cashflow positive sooner. The growth property requires more money from you. But it can build substantially more wealth.
Neither is automatically the better investment. It depends on whether you're trying to build wealth over time or earn more rental income along the way.
The type of property you choose depends on your stage in life.
There are two stages in property investment.
These investors are focused on building wealth.
They’re often 10 to 25 years away from retirement or needing a passive income.
Growth properties often suit investors at this stage.
Why? Working professionals aren't concerned about creating a passive income immediately. They already earn an income.
Instead, they want to build wealth for the future. And, they can afford to wait out the time it takes for houses to slowly increase in value.
Once you retire, you’ve already built your wealth. And your primary concern is cashflow.
Yield properties often suit people at this stage in life.
Why? These people don’t have cashflow coming from their job. So now they want to get a return from their wealth.
Often, at this stage, they'll buy a yield property without a mortgage (or a very low mortgage). They then live off the property’s rental income.
Here's how the numbers tend to look when you buy a yield property without a mortgage:
| Property | Yield |
| Purchase | $600,000 |
| Mortgage | $0 |
| Rent | $36,000 |
| Operating Costs | $12,000 |
| Pre-tax cashflow | $24,000 ($462 / week before tax) |
Once an investor can buy yield properties without a mortgage, the cashflow starts to look more attractive.
In this example, owning 2 to 4 mortgage-free yield properties could provide $48,000 to $96,000 a year in cashflow before tax.
However, investors need to build their wealth before moving on to this second stage.
That's why some investors start with growth properties, then move towards yield properties as retirement gets closer.
As of October 2026, at Opes Partners we assume that growth properties will grow in value at 5% to 6% a year. This is as a long-term average. Not a guarantee that this is the grow you will actually get every year.
And we typically recommend growth properties that have a gross yield between 4 – 5.5%.
For yield properties, it’s usually 6%+ gross yield. And we assume that yield properties grow at 3 – 4% per year (as a long-term average).
Our sister-company, Opes Property works with developers to source properties. As at October 2026, these are the types of numbers they tend to use:
| Type | Growth vs Yield | Price | Target yield | Target capital growth | Locations |
| House | Growth | $680,000– $900,000 | 4% - 4.8% | 5% | Canterbury, Kaiapoi, Rolleston, Lincoln, Rangiora, Marshland |
| Townhouse | Growth | $525,000 - $1.25 million | 4% - 5.5% | 5% - 6% | Auckland, Christchurch, Hamilton, Queenstown, Wanaka |
| Dual-key townhouse | Yield | $720,000– $1 million | 6%+ | 3% - 4% | Auckland, Queenstown, Wellington |
Gross rental yields are based on a property's price and expected rental income. Capital growth rates are forecasts of what a property might achieve in the future.
Just remember, they're assumptions, not guarantees. Your actual return will vary.
Property investing comes with trade offs. You often can’t achieve both strong capital growth and a really high yield.
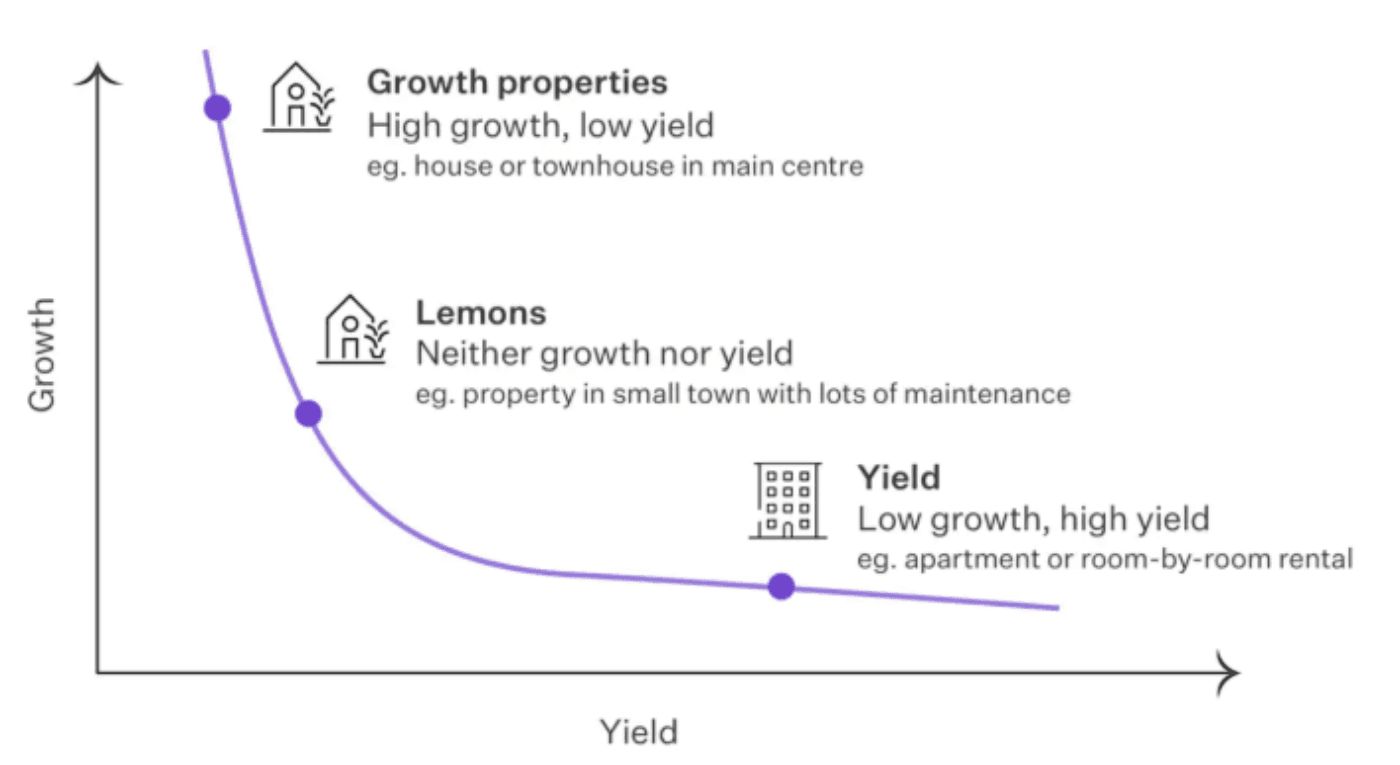
If you try to go after both, you could end up in the middle with a property that doesn't do either particularly well.
Can you have it both ways? Yes. Just not necessarily from the same property.
Your portfolio can have both growth and yield properties. One property might focus on building wealth, while another provides stronger cashflow.
So, rather than asking “How do I get both?”, ask: “What does my portfolio need right now?”
If you're building wealth, that may be growth. If you're preparing to live off your portfolio, that may be yield.
The right property isn't the one that does everything. It's the one that does the job your portfolio needs it to do.
Answer a few questions - and we'll tell you whether you should invest in growth or yield properties.
Take the quizFinancial adviser at Opes. Formerly a senior adviser at one of NZ largest investment firms. Owned 3 properties by 30.
Nefe is a Registered Financial Adviser at Opes Partners with 7 years’ experience in financial services. Before joining Opes, she was a senior adviser at one of New Zealand’s largest investment firms, managing $13 million in KiwiSaver and managed funds. She’s helped clients invest over $26 million in property and owned 3 properties before her 30th birthday.
This article is for your general information. It’s not financial advice. See here for details about our Financial Advice Provider Disclosure. So Opes isn’t telling you what to do with your own money.
We’ve made every effort to make sure the information is accurate. But we occasionally get the odd fact wrong. Make sure you do your own research or talk to a financial adviser before making any investment decisions.
You might like to use us or another financial adviser