Capital Growth
Does population affect capital gains for investment properties in NZ?
You would think that more population would equal more capital growth ... but the data is saying otherwise (in some cases).
Property Investment
8 min read
Author: Andrew Nicol
Founder, 20+ Years' Experience Investing In Property, Author & Host
Reviewed by: Laine Moger
Journalist and Property Educator, holds a Bachelor of Communication (Honours) from Massey University.
“What type of property investor should I be?”
This is still one of the most common questions we get here at Opes Partners.
Because there are so many ways you could invest, a lot of Kiwis struggle to figure out what the right path for them should be.
That’s why in this article you’ll get an unbiased review of the different ways you can become a property investor. That includes New Builds and existing properties.
Now here at Opes Partners we help investors buy New Builds. And we have a range of New Builds you could buy through us, so there is an incentive for me to tell you that New Builds are the perfect buy.
I’m not going to do that. Instead, I’ll honestly explain the pros and cons of each strategy. Then I’ll take a step back and you can decide which is the right strategy for you.
There are a handful of main paths you can take when investing in property. These sit underneath the 3 main umbrella strategies.
The umbrella strategies are:
This is a hands-off investment strategy where you buy a property and wait for it to go up in value.
You can either buy a New Build or an existing property. This is also the strategy we help investors use here at Opes Partners.
Here’s an example of an investor following the New Build strategy:
And here’s an example of someone who buys existing properties:
This is a more active strategy. Here you buy a property and then do it up. Here you also have two options:
Here’s an example of someone following the BRRRR strategy:
And another case study of someone following a Flipping strategy:
This is the most complicated, and expensive strategy. It’s where you become a developer. Again, you have 2 options:
And here are two case studies of investors who are developing properties. The first is an example of a develop to hold. The second is a developer who buys and sells.
Here are the 4 main differences between each of these pathways.
Some property investment strategies take more money than others to get started.
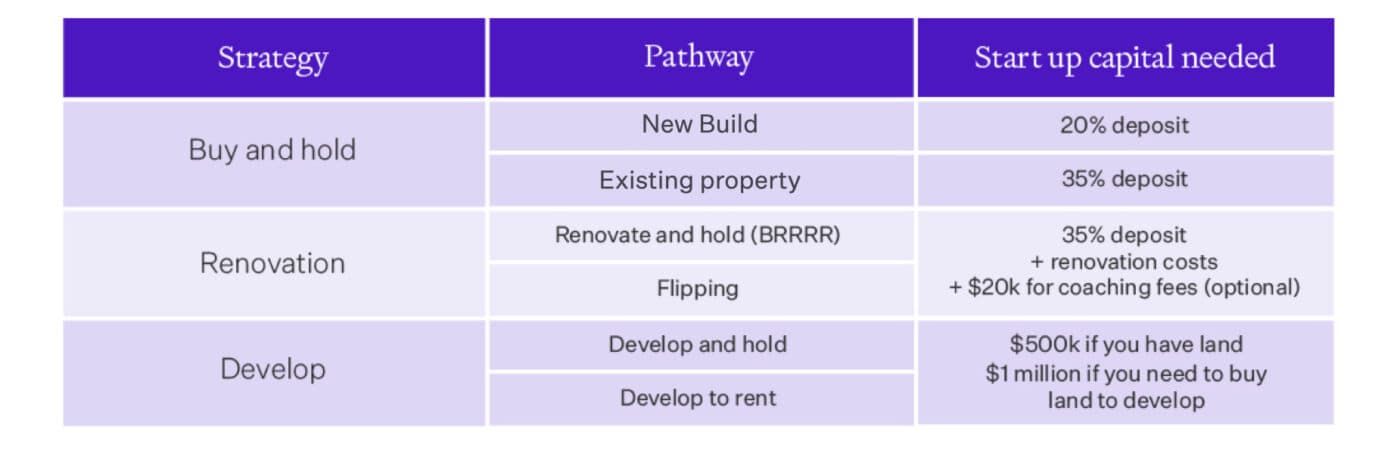
Buy and Hold strategies are the least expensive to get started. They also require the least amount of prior knowledge.
You only need a 20% deposit to buy a New Build. And you only need a 30% deposit to buy an existing property.
But that’s it. There’s no renovation spend required or coaching costs. You buy a finished property and wait.
Renovation strategies can take more money to get going. For starters, you’ll need to buy an existing properties. That means you need a 30% deposit.
You also need to have the money for the renovations. This is usually around the $50k+ mark.
Some investors take this further and also pay to get a property coach. These tend to cost around $20k a year (depending on who you use).
Not everyone uses a property coach, but many investors do.
But you’ve got to get experience somehow. You either pay for the experience of others or you gain your own experience by making mistakes along the way.
A development strategy requires the most start-up capital. You’ll typically need around $500k for construction if you already own the land.
If you’re looking to buy the land as well, you’ll need about a million in cash.
New Build properties used to sidestep a lot more property investment taxes. These days, that advantage has dwindled.
New Builds are still exempt from the Debt-to-Income (DTI) rules, and investors can usually buy them with a smaller deposit.
But when it comes to tax, New Builds and existing properties are now treated much the same.
For instance, both have the same 2-year Bright-Line Test. And investors can now claim 100% of their mortgage interest as a tax-deductible expense, whether they buy a New Build or an existing property.
This applies to New Build, Existing Buy and Hold, and BRRRR strategies.
But flipping properties is different.
If you buy a property intending to renovate and sell it for a profit, you'll generally pay income tax on that profit. That's true even if you hold the property for more than 2 years.
You may also need to pay GST.
The same goes for property development if you're building properties to sell.
So, while New Builds no longer have the big tax advantages they once did, buying and holding a rental property can still be more tax-friendly than flipping or developing properties to sell.
There are also differences in the time each strategy takes.
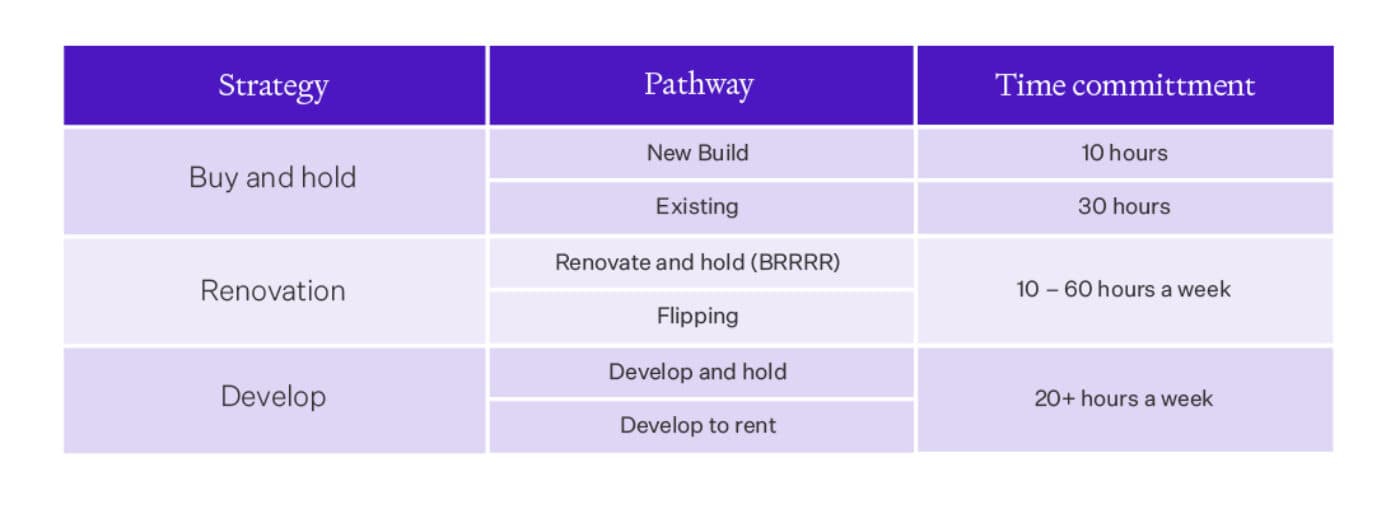
It doesn’t take long to buy a New Build as part of a buy-and-hold strategy. You’ll likely only need about 10 hours to buy and settle the property in total.
If you’re buying existing, you’ll likely spend more time at open homes. So, it might take 30 hours to find, buy and own the property.
But that’s it. A buy-and-hold strategy is a hands-off, low-risk investment option. You buy a property and let the market do its thing for 15 years before coming back to it.
And because your strategy stretches many years, the ups and downs of the market don’t matter that much ... if the long-term trend is up.
If you’re renovating, you’re looking at about 10 hours a week (even if you’re not doing the work yourself).
But the sky is the limit if you want to do the work yourself. Tradesmen make a full-time job out of it.
So, on top of a hefty time commitment, there is a medium amount of risk involved in this. That’s because you might:
Flipping has a bit more risk than a standard renovation strategy. That’s because you have to find a buyer at the other end.
If you don’t, you’ve got an empty house that’s not earning any money … and you’re still paying interest to the bank.
Developing properties means committing at least 20 hours a week. That’s just to project manage the build. That’s not assuming that you’re building the property yourself.
This is a much higher risk, and sometimes you have major price blowouts or delays in construction.
The highest risk and highest amount of time is developing to sell. It takes so much time, even if you’re working with a real estate agent to sell them.
And finally there are differences in the amount of money you might make.

Here at Opes Partners, we assume New Builds and existing properties will go up in value by 5–6% a year, on average, over the long term.
But you probably won't make any instant equity when you first buy.
On top of that, the rent you receive might not cover all your costs.
That means you'll need to put some of your own money towards the property each week. These are called top-ups.
As at October 2026, top-ups are usually around $200–$350 a week.
So, with a buy-and-hold strategy, you mainly make money through your property going up in value over time.
Renovating a property gives you another way to make money.
For example, you might spend $50,000 renovating a property and increase its value by $100,000.
That's $50,000 in extra equity, before buying, selling and other costs.
If you keep the property and rent it out, you could also benefit from its value going up over time. Here at Opes Partners, we assume 5–6% a year, on average, over the long term.
But the rent might not cover all your costs. So, just like a buy-and-hold investor, you may need to top up the property each week.
Flipping is different.
Instead of keeping the property, you renovate it and sell it for a profit.
Because you're buying and selling quickly, you're not relying on the property going up in value over time.
You're relying on the renovations making the property worth more.
For example, you might spend $50,000 on renovations and sell the property for $50,000–$200,000 more than you paid for it.
But that's not all profit. You still need to pay for the renovations, buying and selling costs, interest and tax.
And if the renovation costs more than expected, or the property sells for less than you'd hoped, you could make very little money or even lose money.
If you’re developing to rent, you’ll get the long-term capital growth, but you’ll also hopefully get a 10% uplift during construction.
You are still looking at a cashflow loss during the initial period, while interest rates are high.
If you are developing to sell, you don’t get any market growth, but you do get the instant equity of (hopefully) 10%.
Some investors like to get help when investing in property. The company you talk to depends on which strategy you want.
If you want to invest in New Builds, talk to a property investment company. These businesses will help you create a financial plan.
They will then find you a New Build investment property to buy.
We here at Opes Partners are one example of a property investment company, but there are others out there too. These include:
| Company | Cost to you | Main strategy |
| Opes Partners | $0 | Buy-and-hold, mainly New Builds |
| Property Factory | $0 | New Build property sales |
| Staircase | No financial advice fee | Buy-and-hold |
| Properli | Not stated | Property investment and financial advice |
| Positive Real Estate | $4,995–$9,995 | Buy-and-hold with mentoring |
| Propellor | Reported $6,000 for first purchase | Multiple property strategies |
If you're more interested in renovating properties, here are some property coaching companies worth looking into:
| Company | Cost to you | Main strategy |
| enable.me | Not confirmed | Financial planning and coaching |
| Property Apprentice | Up to $11,000 + GST, plus advice fees | Renovate and hold |
| Wealth Mentor | $25,000–$28,750 incl. GST | Multiple strategies |
| West Property Coaching | $25,000–$35,000 + GST | Renovate and hold |
| Steve Goodey Property Coach | Around $30,000 + GST | Cashflow and renovations |
| Wolfe Property | $25,000–$70,000 incl. GST | BRRRR and multi-unit investing |
Now that you know what the different pathways are, you can pick what strategy is right for you.
If you’re too busy with work or family, a hands-off New Build investment might suit you.
But maybe you’ve got some trade experience and spare time in the evenings. Then you might enjoy taking on some extra risk to make money in a BRRRR project.
Or if you’ve been thinking that your backyard could be a good spot for a development … maybe you’ll go for that option.
There are many ways you can be successful with property. It’s all about knowing the risks and the rewards of each.
Founder, 20+ Years' Experience Investing In Property, Author & Host
Andrew Nicol, Managing Director at Opes Partners, is a seasoned financial adviser and property investment expert with 20+ years of experience. With 40 investment properties, he hosts the Property Academy Podcast, co-authored 'Wealth Plan' with Ed Mcknight, and has helped 1,894 Kiwis achieve financial security through property investment.
This article is for your general information. It’s not financial advice. See here for details about our Financial Advice Provider Disclosure. So Opes isn’t telling you what to do with your own money.
We’ve made every effort to make sure the information is accurate. But we occasionally get the odd fact wrong. Make sure you do your own research or talk to a financial adviser before making any investment decisions.
You might like to use us or another financial adviser